Ahead of AFM, major streaming commitments, new distribution capital, and creator-led properties are reshaping the packages buyers will encounter in Los Angeles.
A24 is bringing Elden Ring to market with international Pay-1 rights reportedly committed to Amazon MGM. Lionsgate has added a capital-backed production relationship with SP Media, while AGC is expanding its approach to creator-led properties.
For independent producers, sales agents, and distributors preparing for AFM, the practical challenge is less about finding another headline transaction than establishing defensible expectations for the specific rights being offered. The comparison now spans territorial advances, downstream licensing potential, distribution commitments, and the allocation of risk between participants.
The American Film Market opens November 10 amid several notable developments in film financing, distribution, and international sales. A24 is bringing a major adaptation to market with an international streaming commitment reportedly in place, Lionsgate has announced a new production and distribution venture, and AGC is expanding its international sales activity into creator-led intellectual property. [1] [2] [3]
These developments offer a preview of the projects, partnerships, and sales strategies entering this year’s market. A24’s streaming arrangement, Lionsgate’s production venture, and AGC’s expansion into creator-led properties each reflect different commercial priorities as companies prepare for AFM.
A24 Brings Elden Ring With Pay-1 Already in View
Screen International reported October 27 that A24 will present Alex Garland’s Elden Ring at AFM after agreeing to an international Pay-1 streaming arrangement with Amazon MGM Studios across what sources described as a substantial footprint. The trade reported an estimated production budget of $175 million–$200 million. Those figures and the scope of the streaming agreement are reported, not disclosed contractual terms. [1]
The notable point for international theatrical buyers is the sequencing. An identifiable streaming counterparty has reportedly been established before the theatrical territories are marketed. That may make the production’s financial profile more legible, but it also means prospective distributors must consider the effect of an existing Pay-1 commitment on their own theatrical release plan, holdbacks, and subsequent exploitation.
Territories should not be assumed to carry equivalent economics merely because the same streaming platform is involved. The material questions include exactly where the agreement applies, the permitted theatrical-to-streaming interval, marketing obligations, exclusivity, and whether other ancillary windows remain available. Those terms have not been publicly detailed in the cited report.
For a buyer, the appropriate comparison is therefore not simply a reported advance for another high-profile title. It is the combination of expected theatrical receipts, the rights retained after Pay-1, local distribution costs, and the likely contractual obligations of the acquisition. A packaged streaming commitment can improve visibility while materially changing the composition of the distributor’s potential return.
Lionsgate and SP Media Link Capital to a Distribution Platform
On October 26, Lionsgate announced a joint venture with Steven Paul’s SP Media. SP Media will make a significant capital investment in ventures intended to expand Lionsgate’s platform and will produce independent features for Lionsgate to distribute. Lionsgate will hold a controlling majority interest in the venture. The official announcement does not publish a transaction value, film-by-film financing terms, or specific territorial rights allocations. [2]
This arrangement is economically different from a third-party distributor negotiating an advance on a fully independent production. The studio’s participation extends beyond a single acquisition: it combines an ongoing supply relationship, a distribution role, and a capital structure whose returns may be realized at more than one level.
That distinction is consequential when comparing offers to producers. A distribution commitment supplied through a venture can carry benefits that are not recorded as a conventional minimum guarantee, while its fees, investment recoupment, and profit participation cannot be inferred from the press release. Nor does a platform-level investment establish the valuation of any one film on the slate.
As producers consider capital proposals alongside territory sales at AFM, the useful discipline is to separate project financing, distributor compensation, and rights acquisition proceeds. Combining them into a single headline number can obscure the film-level cash flows that ultimately determine the producer’s position.
Four Developments, Four Different Valuation Questions
The announcements are informative about market structure, but they are not interchangeable transaction comparables.
| Development | What Is Established | What Still Requires Evidence |
|---|---|---|
| A24 / Elden Ring | Reported international Pay-1 commitment ahead of theatrical sales | Territory coverage, holdbacks, residual windows, distributor cash-flow assumptions |
| Lionsgate / SP Media | Capital-backed venture and an announced distribution relationship | Film-level investment, fees, recoupment positions, and participation economics |
| AGC / creator-led IP | New creator-focused division and an AFM sales title | Audience-to-ticket conversion, territorial concentration, comparable release and licensing returns |
| AFM / audience screenings | Additional public-audience participation in selected market screenings | How screening response translates into territory-specific commercial demand |
What Buyers Can Actually Compare Before AFM
The common challenge across these developments is not an absence of market activity; it is a shortage of public detail about the economics underlying that activity. A studio-backed slate venture, a partially pre-licensed tentpole, and a creator-originated feature do not yield a single measure of territorial value. Their announced structures are useful evidence about buyer behavior, but they cannot replace transactional reference points.
For producers and sales companies preparing a rights position, the more useful analysis combines title-level advance comparisons with territory-specific licensing rates and an assessment of the windows available for sale. For distributors, the same evidence can help distinguish the price paid to secure a package from the plausible revenues and costs associated with exploiting it.
FilmTake’s Global Screen Rights Intelligence provides that broader reference through proprietary advance and licensing data across international markets. The analysis supports more informed comparisons of commercial assumptions, particularly where publicly announced transactions disclose little about the underlying rights economics.
AGC Tests the Commercial Reach of Creator-Led Properties
AGC Studios announced AGC Digital on October 1, describing a division focused on developing franchises with digital creators. On October 22, its international sales arm announced that it would introduce Gossip Goblin’s animated science-fiction feature Gods Don’t Give Gifts to buyers at AFM. The film is also described in industry coverage as AI-generated, adding a production-model question to its creator-led commercial proposition. [3]
A built-in online audience may reduce the cost of initial awareness, but it is not a substitute for evidence of theatrical or licensing demand. An audience may be concentrated outside a buyer’s territory, heavily weighted toward short-form viewing, or responsive to content that does not translate into paid feature-length consumption.
From a sales perspective, the sharper analysis concerns the geographic distribution of the creator’s audience, the comparable performance of similar genre releases, and the availability of downstream buyers. These factors allow an audience claim to be tested against a territory’s revenue opportunity rather than treated as a premium in its own right.
Creator-linked packages may become an increasingly visible part of the market. Their valuation, however, still depends on the distinction between audience reach, monetizable engagement, and distributor collections.
AFM Adds Audiences to Its Market Screenings
AFM has expanded its screening program through a collaboration involving AMC A-List and the B-List Movie Club. Selected screenings and slate presentations can include participating moviegoers alongside industry attendees, with access offered to members of the Los Angeles B-List community. The initiative gives sales companies another setting in which to test presentation and audience response. [4]
Such screenings can help sellers observe reactions to positioning, genre, and presentation, but they should be interpreted with care. A self-selecting Los Angeles moviegoing audience is not a representative sample of viewers in Germany, Japan, or Australia, and enthusiasm at a market event does not disclose the marketing expenditure required to convert interest into admissions.
The broader conference program reflects the same search for new combinations of capital, intellectual property, and distribution. The November 10 New Global Screen Economy Summit and subsequent sessions will address new financing models, creator economics, discovery, and distribution. [5]
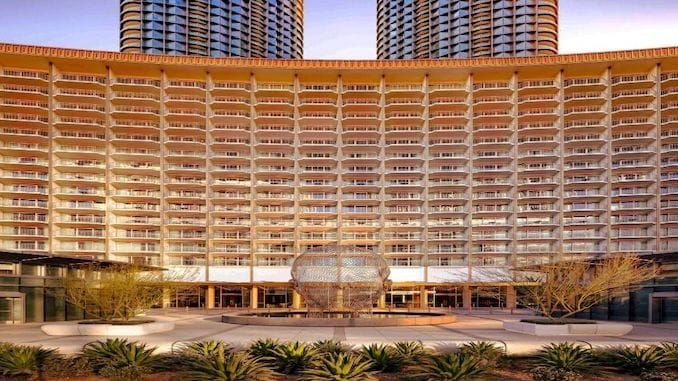
AFM runs November 10–15 at the Fairmont Century Plaza in Los Angeles. Official market screenings are scheduled November 10–13 at AMC Century City 15. [4]
FilmTake Away
The transactions drawing attention ahead of AFM illustrate an increasingly varied set of routes into the international marketplace. Some projects arrive with streaming revenue already assigned; others are supported by integrated capital and distribution relationships or creator-led audience propositions. The headlines establish commercial direction. Assessing the price of rights still available requires a more granular view of advances, licensing revenue, territory demand, and contractual economics.
Territory Value and Licensing Economics
Sources
- Screen International: A24 bringing Alex Garland’s Elden Ring to AFM , October 27, 2026.
- Lionsgate: Lionsgate and Steven Paul’s SP Media launch new joint venture , October 26, 2026.
- AGC Studios press announcements , October 1 and October 22, 2026.
- American Film Market: Expanded screenings and AMC A-List collaboration , September 21, 2026; official screenings schedule .
- American Film Market: Opening summit and expanded conference program , October 15, 2026.